Blogs
Blogs Details
Before applying for a home equity loan or HELOC (Home Equity Line of Credit), it is helpful to understand how much equity you have in your home. Knowing your estimated home equity can give you a clearer picture of your potential borrowing options.
What Is Home Equity?
Home equity is the portion of your home that you own. It is generally calculated by subtracting your outstanding mortgage balance from your home's current market value.
Home Equity Formula
Home Equity = Current Home Value − Outstanding Mortgage Balance
For example, if your home is currently worth $450,000 and your remaining mortgage balance is $275,000:
$450,000 − $275,000 = $175,000
In this example, your estimated home equity is $175,000.
How Do You Determine Your Home's Value?
To calculate your equity accurately, you need a reasonable estimate of your home's current value. You can look at recent sales of similar homes in your area or use available online home-value estimates.
For lending purposes, however, the value used by a lender may be determined through a valuation or appraisal, depending on the loan and lender requirements.
Check Your Current Mortgage Balance
Next, review your latest mortgage statement to find your outstanding principal balance. Make sure you are using the remaining loan balance rather than the original amount you borrowed.
Once you have both figures, subtract the mortgage balance from the estimated property value to calculate your approximate equity.
Does All Your Equity Become Available to Borrow?
Not necessarily. Having $175,000 in home equity does not automatically mean you can borrow $175,000.
When considering a home equity loan or HELOC, lenders may also review factors such as your credit profile, income, existing debts, and loan-to-value (LTV) or combined loan-to-value (CLTV) requirements.
Understanding your equity is an important first step when exploring home equity financing. If you are considering a home equity loan or HELOC, Today’s Home Mortgage can help you better understand your available mortgage options based on your individual financial circumstances.
Disclaimer: This article is for informational purposes only and is not a commitment to lend. Mortgage approval, rates, terms, and program availability are subject to credit approval and applicable requirements.
Related Blogs
Blogs Subheading
Home Equity Loans and HELOCs: When to Use Them and How They Work
Discover how home equity loans and HELOCs work, their key differences, and which option best fits your financial goals as a California homeowner.
When Does Refinancing Make Sense? 7 Key Signs for Homeowners
Discover 7 signs it may be time to refinance your mortgage, lower your payments, access home equity, and achieve your financial goals.
Should You Refinance Your Mortgage Now? 5 Questions to Ask
Thinking about refinancing? Discover 5 important questions every homeowner should ask before refinancing to save money and meet financial goals.
House Hacking in 2026: How Homebuyers Are Living for Free While Building Equity
Learn how house hacking in 2026 can help you reduce your mortgage costs, generate rental income, and build equity faster. Discover financing options for duplexes and multifamily homes that make this wealth-building strategy accessible to first-time buyers.
The Mortgage Impact of Job Hopping: How Career Changes Affect Home Loan Approval
Thinking about buying a home after changing jobs? Learn how career changes can impact mortgage approval and what lenders look for during the loan process.
Buying a Home After Bankruptcy: What Borrowers Need to Know in 2026
Bankruptcy doesn't have to end your homeownership journey. Learn how to qualify for a mortgage, rebuild your finances, and buy a home after bankruptcy in 2026.
Can You Buy a Home With Cryptocurrency Assets?
Learn how cryptocurrency assets can be used in the homebuying process, including lender requirements, down payment rules, and mortgage qualification guidelines.
Why More Families Are Choosing Multi-Generational Homes in 2026
Discover why more families are choosing multi-generational homes in 2026 and learn about the financing options, benefits, and mortgage solutions available.
The Hidden Financial Benefits of Homeownership Beyond Building Equity
Discover the hidden financial benefits of homeownership beyond building equity, including wealth creation, stable housing costs, and long-term financial security.
How Divorce Can Affect Mortgage Approval and Homeownership Plans
Learn how divorce can affect mortgage approval, debt-to-income ratio, and homeownership plans, plus steps to improve your chances of qualifying for a home loan.
The Rise of Co-Buying: Friends Buying Homes Together
Discover how co-buying helps friends achieve homeownership by sharing costs, increasing buying power, and qualifying for a joint mortgage.
How Climate Risks Are Influencing Mortgage Decisions Across the U.S.
Learn how climate risks, flood zones, and insurance requirements can influence mortgage approval, homeownership costs, and real estate decisions.
What Mortgage Lenders Look for Beyond Your Credit Score
Discover the key factors mortgage lenders evaluate beyond your credit score, including income, debt, assets, and employment history.
Home Mortgage Lenders with Fast Approval: How to Speed Up Your Home Loan
Looking for home mortgage lenders with fast approval? Learn practical ways to speed up your home loan process, from getting pre-approved and preparing documents to choosing the right mortgage program. Discover how financial readiness, quick responses, and proper planning can help you move toward closing more efficiently with Today’s Home Mortgage.
What Makes the Best Mortgage Agency?
Choosing the right mortgage agency can make the home financing process easier and more manageable. The best mortgage agency offers personalized loan solutions, a wide range of financing options, experienced professionals, modern technology, and responsive customer service. Whether you're buying a home, refinancing, or exploring other financing options, understanding what to look for can help you make a more confident decision.
Best Mortgage Lenders for Jumbo Loans: What Should You Look For?
Learn what to look for in the best mortgage lenders for jumbo loans, including loan options, qualification requirements, experience, and service.
What Is a Jumbo Loan? Requirements, Benefits & Who Should Consider One
Learn what a jumbo loan is, its requirements and benefits, and who should consider jumbo mortgage financing for high-value homes.
How to Use HELOC for Home Renovations Without Draining Your Savings
Learn how to use a HELOC for home renovations, manage renovation costs, preserve your savings, and make informed home equity financing decisions.
Best Mortgage Lender for Refinancing: What Should You Look For?
Learn what to look for when choosing the best mortgage lender for refinancing, including loan options, costs, experience, and the refinance process.
Best Online Mortgage Lenders in CA: What California Buyers Should Look For
Learn what to look for when choosing an online mortgage lender in California, including loan options, technology, experience, and personalized support.
Top-Rated Mortgage Agency Near You: What Should You Look For?
Learn what to look for in a top-rated mortgage agency, including experience, loan options, personalized guidance, digital services, and local expertise.
Mortgage Lenders for Cash-Out Refinance: Access Your Home Equity with Confidence
Learn how cash-out refinancing works, how homeowners can access home equity, and what to consider when choosing a mortgage lender for a cash-out refinance.
Mortgage Loan Officer Near Me: Find Trusted Home Financing Experts
Learn what a mortgage loan officer does, the benefits of working with a local professional, and how to find trusted home financing experts near you.
How Much House Can I Afford Based on My Income?
Learn how much house you may be able to afford based on your income, monthly debts, down payment, credit profile, interest rate, and other mortgage costs. Explore key factors lenders consider and understand your potential homebuying budget.
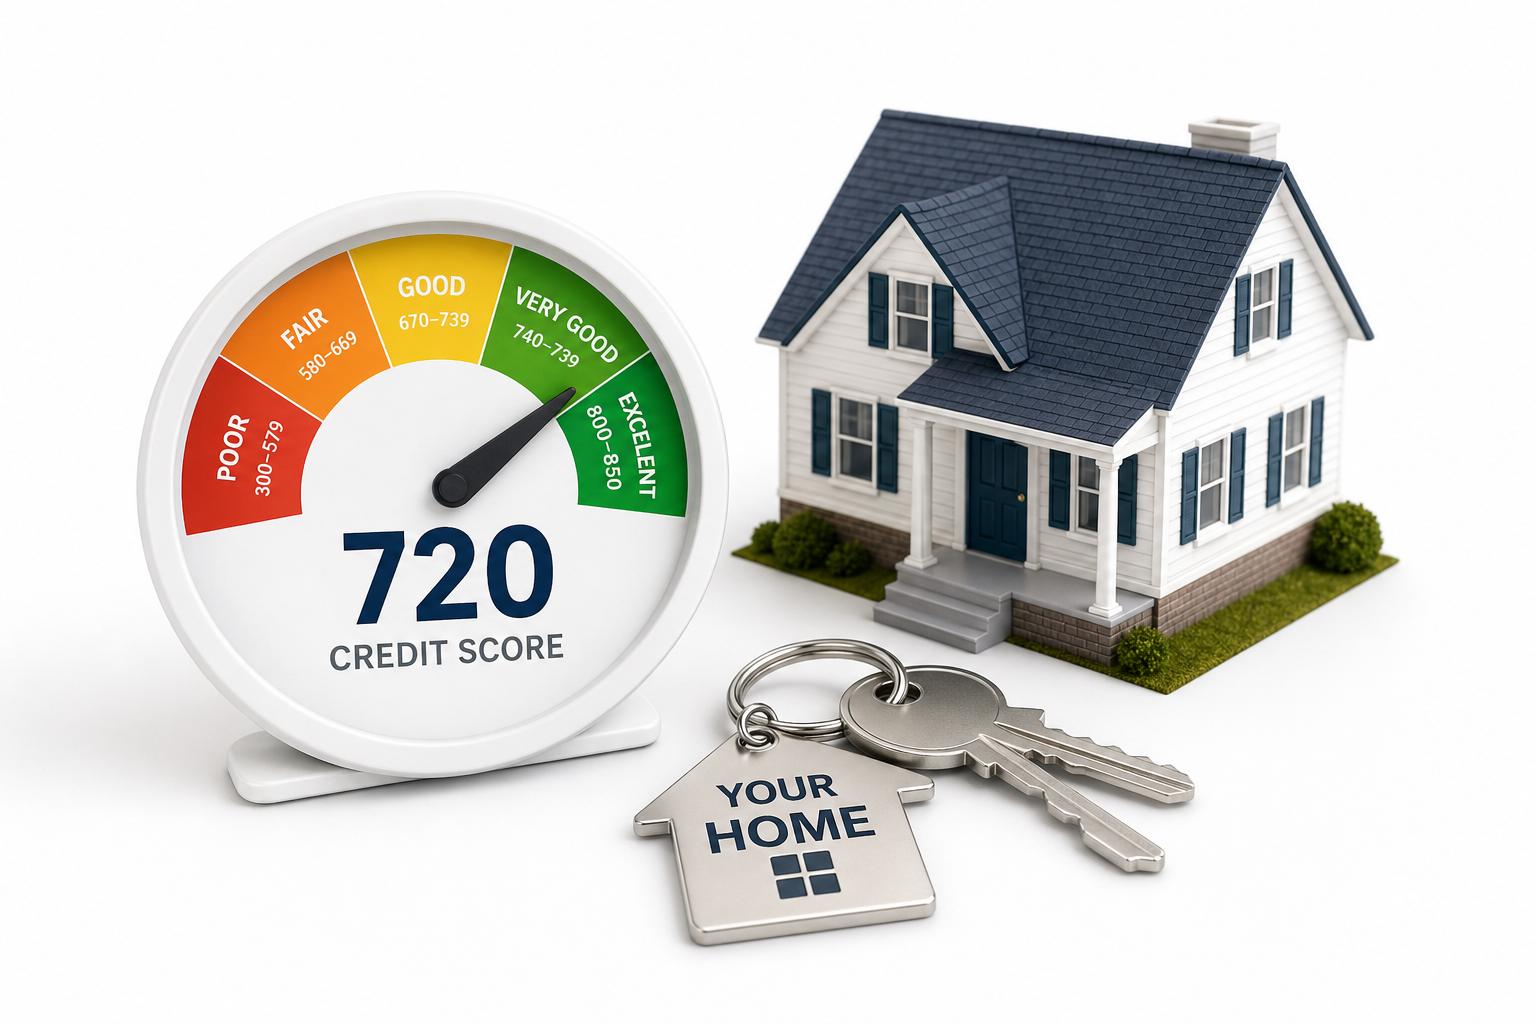
What Is a Good Credit Score to Buy a House?
Your credit score matters when buying a home. Learn what you should know before applying.
How Much Should You Save Before Buying a Home?
Buying a home involves more than saving for a down payment. Learn what expenses to consider so you can prepare your finances with confidence.
How Long Does a Mortgage Refinance Take?
Learn how long a mortgage refinance takes, the steps involved, and what factors may affect your refinancing timeline.
First-Time Homebuyer Mistakes to Avoid
Learn the common first-time homebuyer mistakes to avoid, from budgeting and pre-approval to choosing a mortgage and closing costs.
How Much Down Payment Do You Really Need?
Find out how much down payment you might need and what additional costs to consider when buying a home.
How to Prepare Your Finances for Homeownership
Learn how to prepare your finances for homeownership by managing debt, improving financial readiness, building savings, and exploring mortgage options.
How Refinancing Can Change Your Monthly Mortgage Payment
See how refinancing may change your monthly mortgage payment, loan term, interest rate, and costs.
How Credit Score Affects Your Refinance Rate
Learn how your credit score may affect refinance rates, loan terms, and your mortgage options.
How Much Equity Do You Need to Refinance Your Mortgage?
Learn how home equity, LTV, credit, and loan type can affect your mortgage refinance options.
Home Equity Loan vs. HELOC: What Is the Difference?
Compare home equity loans and HELOCs to understand their key differences, features, and repayment options.
How Does a Home Equity Loan Work?
Learn how home equity loans work, from borrowing against equity to repayment and loan terms.
How Does a HELOC Work?
Learn how a HELOC works, including draw and repayment periods, variable rates, borrowing limits, and home equity requirements.
How Much Home Equity Do You Need for a Loan?
Learn how much home equity you may need and what lenders consider when reviewing a loan or HELOC.
How Much Can You Borrow with a Home Equity Loan
Discover how home value, mortgage balance, credit score, and income affect your potential home equity loan amount.
HELOC Requirements: What Do You Need to Qualify?
Explore HELOC requirements, from credit score and home equity to income, debts, and required documents.
What Can You Use a Home Equity Loan For?
Explore common uses for a home equity loan, including renovations, debt consolidation, and major planned expenses.
Home Equity Loan Requirements: What Do You Need to Qualify?
Learn about home equity loan requirements, including credit score, home equity, income, debt-to-income ratio, and property documentation.
Best Mortgage Agency in California: Home Loan Options from Today’s Home Mortgage
Explore California mortgage options, including home purchase loans, refinancing, HELOCs, and home equity loans.