Blogs
When Does Refinancing Make Sense? 7 Key Signs for Homeowners
When Does Refinancing Make Sense? 7 Key Signs for Homeowners
Refinancing can reset your financial trajectory, but only when Does Refinancing Make Sense? 7 Key Signs for Homeowners
Refinancing can reset your financial trajectory, but only when the timing and circumstances align. Too many California homeowners either refinance impulsively (and pay thousands in unnecessary fees) or miss golden windows of opportunity because they weren't paying attention to the right signals. Knowing when to refinance is just as important as knowing how.
Here are seven key signs that it may be time to refinance your mortgage, brought to you by the team at Today's Home Mortgage in Lake Forest, CA.

Sign 1: Interest Rates Have Dropped Significantly
This is the classic refinance trigger. If current mortgage rates in California are noticeably lower than the rate on your existing loan, you may be able to dramatically reduce your monthly payment or total interest paid over the life of the loan. Even a modest reduction on a large California mortgage can translate to significant savings.
Sign 2: Your Credit Score Has Improved
If your credit score has risen by 50 or more points since you took out your mortgage, you may now qualify for a materially better interest rate even if market rates haven't changed. A strong credit score is one of the biggest determinants of the rate you're offered, and a jump from 680 to 740 can open doors to much better mortgage terms.
Sign 3: You Want to Switch From an ARM to a Fixed-Rate Loan
If you have an adjustable-rate mortgage (ARM) and your fixed-rate period is nearing its end, or if rate adjustment volatility is creating financial stress, refinancing into a fixed-rate loan locks in predictability and stability. This is especially valuable for Orange County homeowners with large loan balances who can't afford payment uncertainty.
Sign 4: You Want to Eliminate PMI
If you originally purchased your home with less than 20% down and have been paying private mortgage insurance (PMI) or FHA mortgage insurance premiums (MIP), refinancing into a conventional loan once you've reached 20% equity can eliminate that cost. In California's high-value markets, PMI can easily represent $200–$500 per month—a significant ongoing expense worth eliminating.
Sign 5: You Want to Access Your Home Equity
A cash-out refinance allows you to replace your existing mortgage with a larger loan and take the difference in cash. If you've accumulated substantial equity in your Lake Forest or Orange County home—and you have a worthwhile use for the funds—a cash-out refi can provide capital at rates far below credit cards or personal loans.
Sign 6: You Want to Pay Off Your Home Faster
Refinancing from a 30-year mortgage into a 15-year loan dramatically increases the speed at which you build equity and pay off your home. While your monthly payment will likely increase, the total interest savings over the life of the loan can be staggering. For California homeowners who are financially comfortable and want to build wealth faster, this can be an exceptional strategy.
Sign 7: Your Life Circumstances Have Changed
Marriage, divorce, the arrival of children, an inheritance, a major income increase, or a significant change in employment can all alter what kind of mortgage makes the most sense for your household. Refinancing after a major life change allows you to restructure your mortgage to match your new financial reality, whether that means freeing up cash flow, removing a co-borrower, or building equity more aggressively.
A Word of Caution: Not Every 'Sign' Means Refinance Immediately
Each of these signs is meaningful, but none of them in isolation automatically means you should refinance right now. Your break-even timeline, closing costs, remaining loan balance, and how long you plan to stay in the home all factor into the true value of a refinance. A quick, no-obligation analysis from a licensed mortgage professional is the best way to know for certain.
Get Your Free Refinance Analysis From Today's Home Mortgage
At Today's Home Mortgage in Lake Forest, CA, we've helped thousands of California homeowners navigate the refinancing decision with clarity and confidence. Our experienced team offers honest, personalized guidance—never a one-size-fits-all approach.
If any of these seven signs resonate with your situation, it's time to have a conversation. Call (800) 396-1496, email approval@todayshomemortgage.com, or visit todayshomemortgage.com to speak with a licensed mortgage advisor today. Our office is located at 27 Orchard Rd #111, Lake Forest, CA 92630, and we're ready to help you make the most of your home investment.
Related Blogs
Home Equity Loans and HELOCs: When to Use Them and How They Work
Discover how home equity loans and HELOCs work, their key differences, and which option best fits your financial goals as a California homeowner.
Should You Refinance Your Mortgage Now? 5 Questions to Ask
Thinking about refinancing? Discover 5 important questions every homeowner should ask before refinancing to save money and meet financial goals.
House Hacking in 2026: How Homebuyers Are Living for Free While Building Equity
Learn how house hacking in 2026 can help you reduce your mortgage costs, generate rental income, and build equity faster. Discover financing options for duplexes and multifamily homes that make this wealth-building strategy accessible to first-time buyers.
The Mortgage Impact of Job Hopping: How Career Changes Affect Home Loan Approval
Thinking about buying a home after changing jobs? Learn how career changes can impact mortgage approval and what lenders look for during the loan process.
Buying a Home After Bankruptcy: What Borrowers Need to Know in 2026
Bankruptcy doesn't have to end your homeownership journey. Learn how to qualify for a mortgage, rebuild your finances, and buy a home after bankruptcy in 2026.
Can You Buy a Home With Cryptocurrency Assets?
Learn how cryptocurrency assets can be used in the homebuying process, including lender requirements, down payment rules, and mortgage qualification guidelines.
Why More Families Are Choosing Multi-Generational Homes in 2026
Discover why more families are choosing multi-generational homes in 2026 and learn about the financing options, benefits, and mortgage solutions available.
The Hidden Financial Benefits of Homeownership Beyond Building Equity
Discover the hidden financial benefits of homeownership beyond building equity, including wealth creation, stable housing costs, and long-term financial security.
How Divorce Can Affect Mortgage Approval and Homeownership Plans
Learn how divorce can affect mortgage approval, debt-to-income ratio, and homeownership plans, plus steps to improve your chances of qualifying for a home loan.
The Rise of Co-Buying: Friends Buying Homes Together
Discover how co-buying helps friends achieve homeownership by sharing costs, increasing buying power, and qualifying for a joint mortgage.
How Climate Risks Are Influencing Mortgage Decisions Across the U.S.
Learn how climate risks, flood zones, and insurance requirements can influence mortgage approval, homeownership costs, and real estate decisions.
What Mortgage Lenders Look for Beyond Your Credit Score
Discover the key factors mortgage lenders evaluate beyond your credit score, including income, debt, assets, and employment history.
Home Mortgage Lenders with Fast Approval: How to Speed Up Your Home Loan
Looking for home mortgage lenders with fast approval? Learn practical ways to speed up your home loan process, from getting pre-approved and preparing documents to choosing the right mortgage program. Discover how financial readiness, quick responses, and proper planning can help you move toward closing more efficiently with Today’s Home Mortgage.
What Makes the Best Mortgage Agency?
Choosing the right mortgage agency can make the home financing process easier and more manageable. The best mortgage agency offers personalized loan solutions, a wide range of financing options, experienced professionals, modern technology, and responsive customer service. Whether you're buying a home, refinancing, or exploring other financing options, understanding what to look for can help you make a more confident decision.
Best Mortgage Lenders for Jumbo Loans: What Should You Look For?
Learn what to look for in the best mortgage lenders for jumbo loans, including loan options, qualification requirements, experience, and service.
What Is a Jumbo Loan? Requirements, Benefits & Who Should Consider One
Learn what a jumbo loan is, its requirements and benefits, and who should consider jumbo mortgage financing for high-value homes.
How to Use HELOC for Home Renovations Without Draining Your Savings
Learn how to use a HELOC for home renovations, manage renovation costs, preserve your savings, and make informed home equity financing decisions.
Best Mortgage Lender for Refinancing: What Should You Look For?
Learn what to look for when choosing the best mortgage lender for refinancing, including loan options, costs, experience, and the refinance process.
Best Online Mortgage Lenders in CA: What California Buyers Should Look For
Learn what to look for when choosing an online mortgage lender in California, including loan options, technology, experience, and personalized support.
Top-Rated Mortgage Agency Near You: What Should You Look For?
Learn what to look for in a top-rated mortgage agency, including experience, loan options, personalized guidance, digital services, and local expertise.
Mortgage Lenders for Cash-Out Refinance: Access Your Home Equity with Confidence
Learn how cash-out refinancing works, how homeowners can access home equity, and what to consider when choosing a mortgage lender for a cash-out refinance.
Mortgage Loan Officer Near Me: Find Trusted Home Financing Experts
Learn what a mortgage loan officer does, the benefits of working with a local professional, and how to find trusted home financing experts near you.
How Much House Can I Afford Based on My Income?
Learn how much house you may be able to afford based on your income, monthly debts, down payment, credit profile, interest rate, and other mortgage costs. Explore key factors lenders consider and understand your potential homebuying budget.
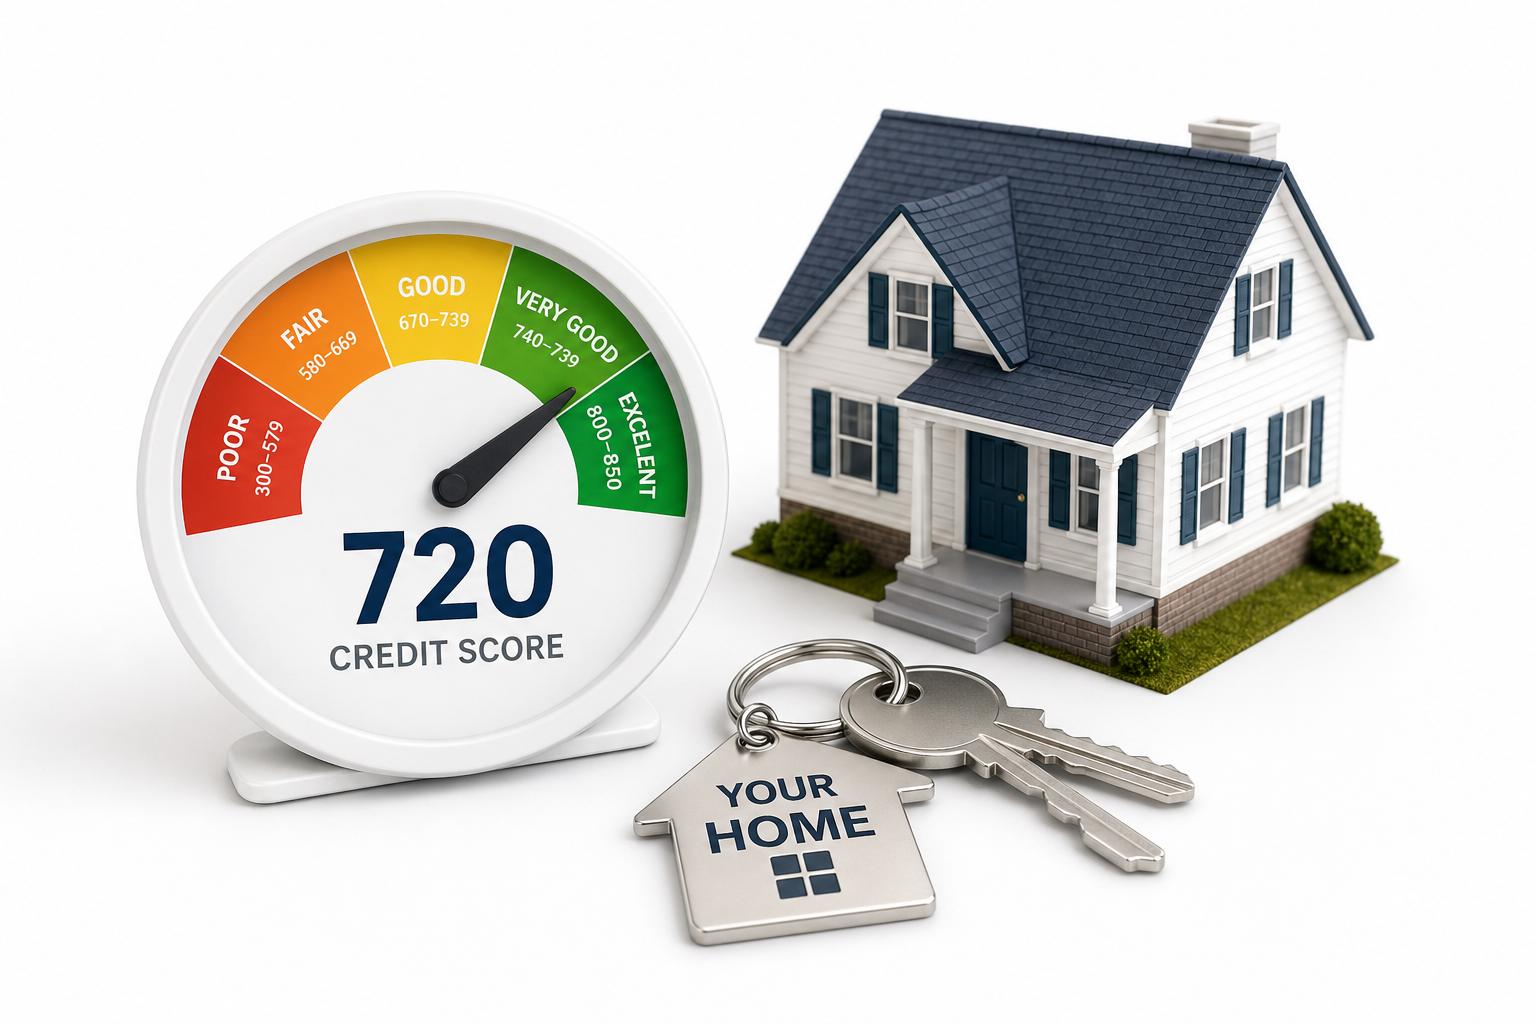
What Is a Good Credit Score to Buy a House?
Your credit score matters when buying a home. Learn what you should know before applying.
How Much Should You Save Before Buying a Home?
Buying a home involves more than saving for a down payment. Learn what expenses to consider so you can prepare your finances with confidence.
How Long Does a Mortgage Refinance Take?
Learn how long a mortgage refinance takes, the steps involved, and what factors may affect your refinancing timeline.
First-Time Homebuyer Mistakes to Avoid
Learn the common first-time homebuyer mistakes to avoid, from budgeting and pre-approval to choosing a mortgage and closing costs.
How Much Down Payment Do You Really Need?
Find out how much down payment you might need and what additional costs to consider when buying a home.
How to Prepare Your Finances for Homeownership
Learn how to prepare your finances for homeownership by managing debt, improving financial readiness, building savings, and exploring mortgage options.
How Refinancing Can Change Your Monthly Mortgage Payment
See how refinancing may change your monthly mortgage payment, loan term, interest rate, and costs.
How Credit Score Affects Your Refinance Rate
Learn how your credit score may affect refinance rates, loan terms, and your mortgage options.
How Much Equity Do You Need to Refinance Your Mortgage?
Learn how home equity, LTV, credit, and loan type can affect your mortgage refinance options.
Home Equity Loan vs. HELOC: What Is the Difference?
Compare home equity loans and HELOCs to understand their key differences, features, and repayment options.
How Does a Home Equity Loan Work?
Learn how home equity loans work, from borrowing against equity to repayment and loan terms.
How Does a HELOC Work?
Learn how a HELOC works, including draw and repayment periods, variable rates, borrowing limits, and home equity requirements.
How Much Home Equity Do You Need for a Loan?
Learn how much home equity you may need and what lenders consider when reviewing a loan or HELOC.
How Much Can You Borrow with a Home Equity Loan
Discover how home value, mortgage balance, credit score, and income affect your potential home equity loan amount.
HELOC Requirements: What Do You Need to Qualify?
Explore HELOC requirements, from credit score and home equity to income, debts, and required documents.
How to Calculate Your Home Equity Before Applying for a Loan
Learn how to calculate home equity using your home's value and mortgage balance, and understand how much equity may be available to borrow.
What Can You Use a Home Equity Loan For?
Explore common uses for a home equity loan, including renovations, debt consolidation, and major planned expenses.
Home Equity Loan Requirements: What Do You Need to Qualify?
Learn about home equity loan requirements, including credit score, home equity, income, debt-to-income ratio, and property documentation.
Best Mortgage Agency in California: Home Loan Options from Today’s Home Mortgage
Explore California mortgage options, including home purchase loans, refinancing, HELOCs, and home equity loans.